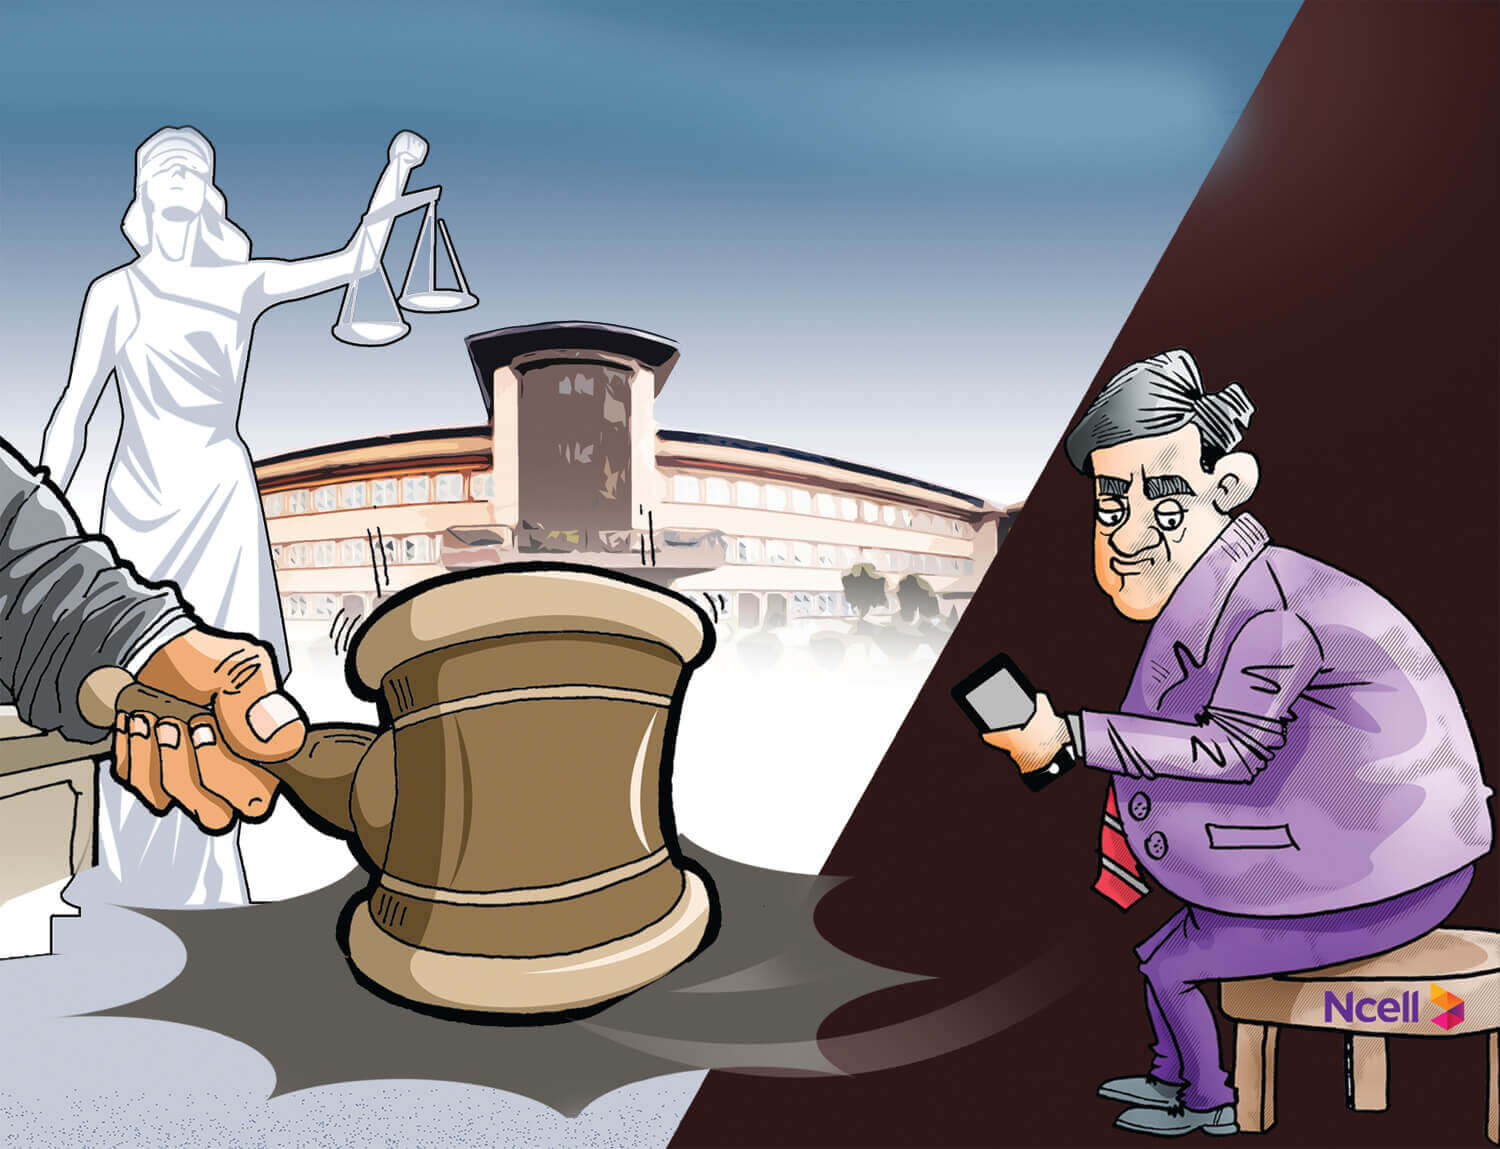
The spate of investment treaty arbitrations that have inundated developing countries in recent times has now reached Nepal. At stake is a Rs39.06 billion tax imposed by the Large Taxpayers Office (LTO) on Ncell, following a decision of the Supreme Court.
Ncell subsequently contested the LTO tax assessment, submitting that it is liable to pay only Rs14.5 billion. It also obtained an interlocutory interim stay from the Supreme Court on these grounds.
The initiation of investment treaty arbitration by Axiata Investment UK Ltd (Axiata UK) through an intermediate special purpose vehicle not directly investing in Nepal, while challenging the same action before the Supreme Court of Nepal and bypassing other statutory remedies, raises several questions as to the use of investment treaty arbitration and the International Centre for Settlement of Investment Disputes (ICSID).
Read also:
Ncell ruling opens a can of worms, Semanta Dahal
Supreme Court weights in on Ncell tax dispute, Sharad Ojha
Axiata UK filed a request for arbitration before the ICSID against the Government of Nepal regarding the capital gains tax levied by Nepal’s tax authorities on the indirect transfer to Axiata UK of an 80% stake in Ncell through the sale of Reynolds Holdings Limited, by the previous foreign investor, TeliaSonera Norway Nepal Holdings AS to Axiata UK.
The arbitration was initiated on the basis of the bilateral investment treaty between the governments of Nepal and the UK (UK-Nepal BIT) on 2 March 1993. In parallel, Ncell has also initiated proceedings before the Supreme Court of Nepal challenging the CGT assessment by the tax authorities.
In doing so, Ncell and its indirect shareholder Axiata UK have not availed statutory remedies otherwise available under Nepal's law to challenge the assessment. This presents the government with some credible arguments to resist the investment treaty claims.
First, it is doubtful whether Axiata UK’s indirect acquisition of Ncell’s shares qualifies as an ‘investment’ in terms of Article 1(a) read with Article 8(1) of the UK-Nepal BIT. Axiata UK’s role in the transaction is limited to its acquisition of Reynolds, which owns 80% of the shares of Ncell.
Moreover, Axiata UK is a wholly owned subsidiary of Malaysia-based Axiata Group Berhad. The Government of Nepal could argue that Axiata UK Ltd has no real interest in the transaction and is merely being used as a vehicle to bypass the jurisdictional hurdle of the UK-Nepal BIT.
Previous investment treaty arbitrations have found that a mere passive investor, such as a company which conducts no business of its own but merely holds shares in a company incorporated in the host state, will not be able to invoke the jurisdiction under a bilateral investment treaty.